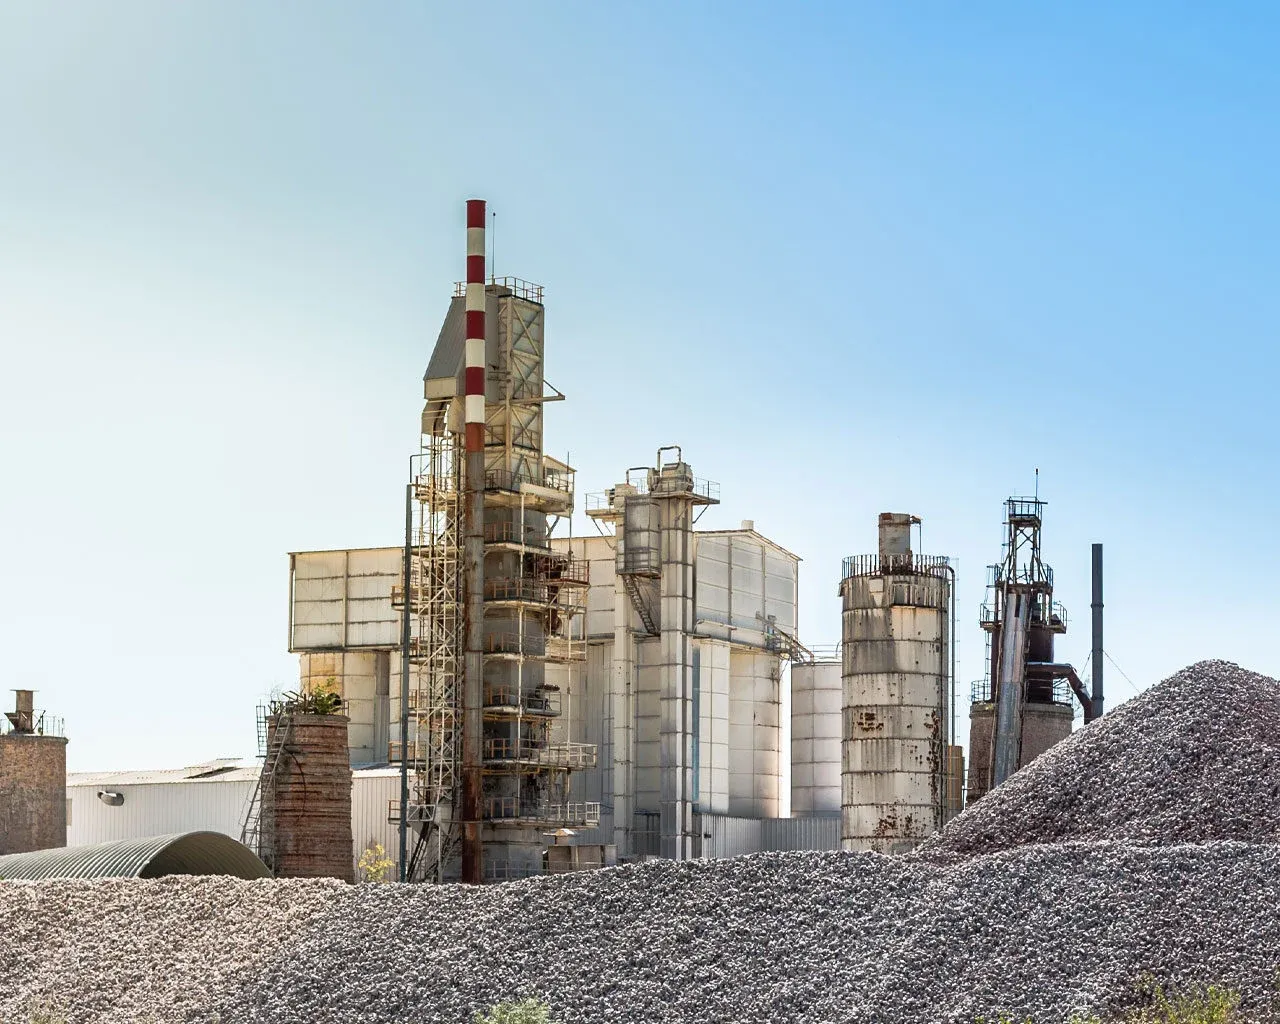
NEW DELHI, Oct. 8: India’s cement industry is facing renewed pressure on profitability as rising fuel and transportation costs threaten to offset stronger demand and recent price increases, potentially keeping cement stocks under pressure over the coming quarters.
Cement sales volumes are estimated to have increased by 6–7 per cent year-on-year during the July–September quarter of the 2026-27 financial year, despite the monsoon season traditionally slowing construction activity.
However, higher energy costs, particularly imported petroleum coke, could reduce operating margins and delay earnings improvements until the final quarter of the financial year.
Imported petroleum coke prices have increased by approximately 30–35 per cent compared with the preceding quarter, while thermal coal prices have risen by 1–2 per cent. Higher crude oil and natural gas prices have also pushed up packaging and transportation expenses.
The increases are significant for cement manufacturers because fuel and freight account for a substantial portion of production and distribution costs.
Industry estimates suggest that average cement realisations may have improved by 1–2 per cent quarter-on-quarter following price increases during August and September. Nevertheless, the improvement may not be sufficient to compensate for rising input costs.
As a result, earnings before interest, tax, depreciation and amortisation (EBITDA) per tonne are expected to decline both sequentially and year-on-year for several manufacturers.
Companies including UltraTech Cement, Shree Cement and JK Cement are believed to have gained market share during the September quarter, although stronger sales volumes may not translate into proportionate earnings growth.
Cement prices had weakened slightly during July and August before recovering in September as demand improved. The recovery helped manufacturers increase selling prices across several regions.
The industry’s ability to sustain these increases will be important in determining profitability during the second half of the financial year.
Energy costs are also expected to affect earnings with a delay. Cement companies typically maintain fuel inventories, meaning higher petroleum coke and coal prices can take three months or longer to appear fully in their operating expenses.
Consequently, elevated fuel costs incurred during the September quarter could continue affecting financial results during October–December.
The continuing conflict in West Asia has added uncertainty to international energy markets, making it difficult for manufacturers to predict when input costs might stabilise.
Demand conditions, meanwhile, remain comparatively favourable.
Cement production recorded double-digit year-on-year growth during July and August, according to trends in the Index of Industrial Production.
Industry demand is projected to expand by approximately 7–8 per cent during FY27, supported by public infrastructure expenditure, housing construction and private-sector investment.
Over the longer term, annual cement volume growth is expected to remain in the range of 6–8 per cent between FY27 and FY29.
Government investment in roads, railways, metro systems and urban infrastructure is expected to remain an important source of demand.
Private investment in manufacturing facilities, renewable energy projects, data centres and industrial infrastructure could provide additional support.
However, demand may remain uneven across regions in the near term.
Erratic monsoon conditions could affect rural construction activity, while the festive season may temporarily slow project execution during the December quarter.
Construction restrictions imposed to control air pollution in northern India could also affect cement consumption in some markets.
Manufacturers will therefore face the challenge of maintaining selling prices without weakening demand or losing market share.
The industry continues to have surplus production capacity, with several major companies pursuing expansion plans. Excess capacity can create pressure to offer discounts, particularly when demand growth varies between regions.
Any aggressive price competition could further weaken profitability at a time when energy costs are already elevated.
Industry consolidation may help improve pricing discipline over the medium term, although the immediate earnings outlook remains dependent on fuel prices and demand conditions.
Manufacturers are increasingly investing in renewable energy, waste heat recovery systems and alternative fuels to reduce their dependence on conventional energy sources.
These measures can lower production costs over time, but their benefits may not be sufficient to offset sudden increases in imported fuel prices.
Companies with access to domestic coal supplies, efficient logistics networks and larger production facilities may be better positioned to manage cost pressures.
Strong balance sheets and relatively low debt levels could also provide an advantage as manufacturers continue investing in capacity expansion.
For investors, the principal concern is the gap between improving cement consumption and the industry’s ability to convert higher sales into stronger earnings.
Despite expectations of healthy demand growth, analysts see limited scope for immediate earnings upgrades because of the pressure on operating margins.
A meaningful improvement in profitability may not emerge until the January–March quarter of FY27, unless international energy prices ease earlier.
The outlook for cement stocks will therefore depend on whether manufacturers can sustain recent price increases, contain fuel and freight expenses, and benefit from the anticipated recovery in construction demand.
While India’s infrastructure and housing requirements continue to support the industry’s longer-term growth prospects, elevated input costs could keep near-term earnings and share prices under pressure.