MUMBAI, Sept. 23
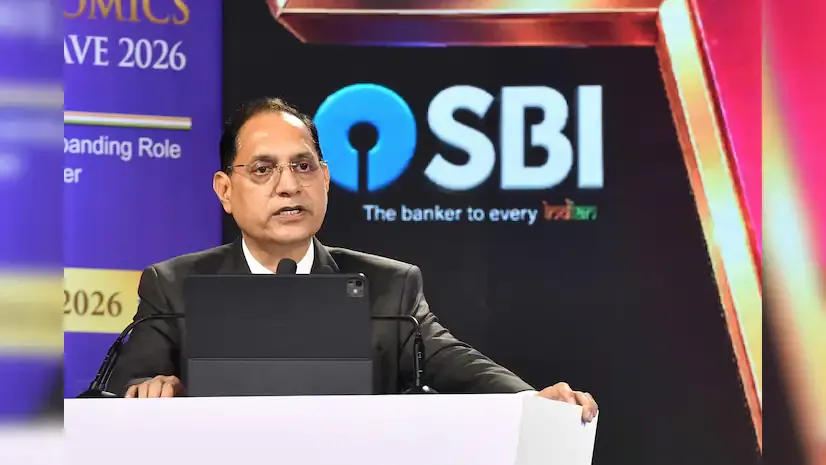
India’s securities regulator is considering further measures to make the country’s derivatives market more balanced, Securities and Exchange Board of India Chairman Tuhin Kanta Pandey said on Wednesday, as the regulator continues to examine the rapid growth and changing structure of futures and options trading.
Pandey said SEBI was studying the derivatives market closely and would consider whether additional steps were required, while stressing that any intervention would be based on data rather than a predetermined regulatory position.
“We will see how we can make the derivatives market more balanced,” Pandey said on the sidelines of an event in Mumbai, according to Business Standard.
His remarks follow a series of regulatory changes aimed at the equity derivatives segment, particularly index options, where participation by individual traders expanded sharply in recent years.
SEBI’s concern has centred partly on the heavy losses suffered by individual participants in futures and options trading. Its own studies have previously found that a large majority of individual traders in the equity F&O segment lost money, raising questions about whether rapid growth in speculative activity was serving the wider purpose of the derivatives market.
Derivatives perform an important role in financial markets by allowing investors and businesses to hedge risks and improve price discovery. But excessive speculative activity, particularly among inexperienced retail participants using leveraged products, can expose investors to losses substantially larger than they may initially expect.
SEBI has consequently sought to distinguish between preserving derivatives as legitimate risk-management instruments and addressing market structures that may encourage excessive short-term speculation.
Pandey indicated that the regulator’s objective was not simply to reduce derivatives volumes.
The focus, he said, was on achieving a better balance between the cash and derivatives markets and ensuring that derivatives activity remained connected to the underlying securities market.
That distinction is important for India, where derivatives turnover has expanded far more rapidly than activity in the cash equity market.
SEBI has already introduced measures intended to curb excessive speculation and strengthen risk controls. These have included changes to contract sizes, limits on weekly expiries, upfront collection of option premiums and additional monitoring of positions around expiry.
The regulator has also moved to strengthen intraday monitoring of index derivatives positions and reduce the risks associated with very large exposures being accumulated close to contract expiry.
Pandey’s latest comments suggest SEBI is assessing the impact of those measures before determining whether another round of intervention is necessary.
Any further changes are likely to be watched closely by stock exchanges, brokers, proprietary trading firms and individual investors because derivatives have become an important source of trading activity and revenue across India’s capital markets.
The growth of options trading in particular has transformed market participation. Low upfront option premiums and easy access through mobile trading platforms have brought large numbers of individual investors into products that can involve complicated pricing and significant leverage.
SEBI’s research into trading outcomes has sharpened regulatory attention on this segment. The regulator has repeatedly emphasised that high turnover should not automatically be treated as evidence of healthy market development if participation produces persistent losses for large numbers of investors.
At the same time, overly restrictive regulation carries its own risks. Derivatives provide liquidity and allow institutional investors, foreign portfolio investors, asset managers and other market participants to hedge exposures efficiently. Measures that significantly reduce liquidity could increase transaction costs or push some activity towards other products or markets.
That leaves SEBI facing a question of calibration rather than simply whether derivatives trading should expand or contract.
Pandey said the regulator would continue examining market data before deciding on further measures. That approach is consistent with SEBI’s recent efforts to evaluate the effect of earlier reforms rather than repeatedly changing the framework before their impact becomes visible.
The regulator is also looking more broadly at India’s capital markets as household participation in financial assets increases.
Millions of investors have entered equities and mutual funds over the past several years, aided by digital platforms, simplified account opening and wider access to market information. The expansion has helped deepen India’s capital markets, but it has also increased the regulator’s responsibility to ensure that inexperienced investors understand the risks attached to more complex products.
Derivatives sit at the centre of that challenge because their accessibility can make sophisticated leveraged instruments appear similar to ordinary share trading.
SEBI’s response so far has therefore combined market-structure reforms with investor-protection measures rather than seeking to prohibit retail participation.
Pandey’s use of the word “balanced” points to the direction of the regulator’s thinking. The issue is not merely the absolute size of India’s derivatives market, but its relationship with the underlying cash market, the concentration of activity in short-duration contracts and the trading outcomes experienced by different categories of participants.
The next phase of reform will depend on what SEBI’s analysis shows after the measures already introduced have had time to work.
For traders and market intermediaries, that means India’s derivatives framework is likely to remain under active regulatory review. The regulator has not announced another set of restrictions, but Pandey’s comments make clear that it has not finished examining whether the present structure provides the balance it wants between liquidity, hedging, speculation and investor protection.