MUMBAI, Sept. 23
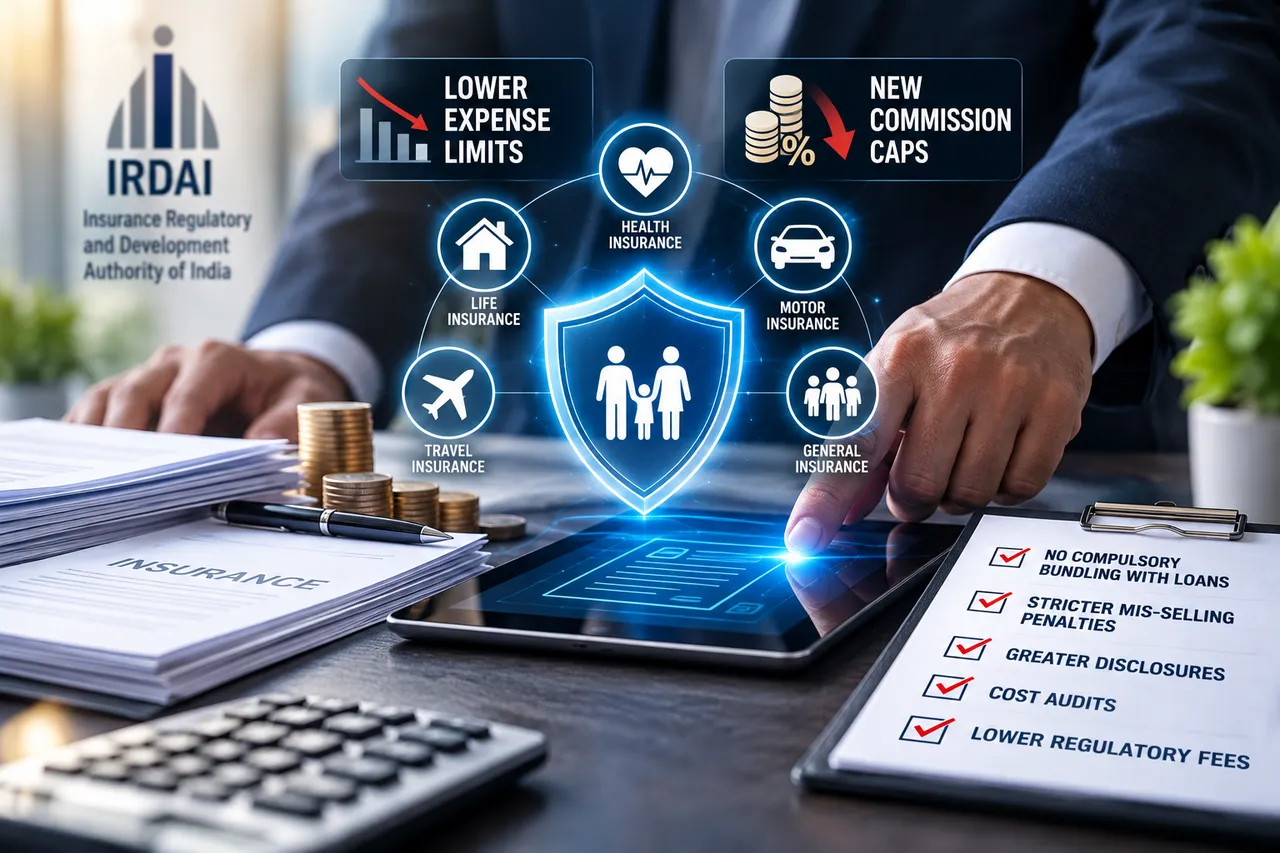
India’s insurance regulator has proposed tighter limits on insurers’ management expenses and a new system of commission caps, alongside restrictions on compulsory insurance bundling with loans and stronger penalties for mis-selling, in a broad overhaul aimed at reducing costs for policyholders.
Under a consultation paper released on Wednesday, the Insurance Regulatory and Development Authority of India (IRDAI) has proposed that life insurers reduce company-level expenses of management, or EoM, to 15 per cent of gross direct premium income within two years and 12.5 per cent within five years.
Life insurers whose expenses were already below the proposed benchmark in 2024-25 would be expected to bring the ratio down to 10 per cent within five years, which the regulator has identified as its longer-term objective for the sector.
General insurers would face a similar tightening. IRDAI has proposed changing the benchmark for their management expenses from gross written premium to domestic gross direct premium income and reducing the permitted limit from 30 per cent to 20 per cent over five years. General insurers already operating below the benchmark would have a five-year target of 20 per cent.
IRDAI said lower expense limits should reduce the overall cost of insurance, increase the risk pool available to general insurers and improve policyholder returns from life insurance savings products. The reductions would be phased in to give companies time to adjust their cost structures.
The proposals could affect one of the most important components of insurance distribution: commissions paid to agents and other intermediaries.
Rather than applying a single commission structure, IRDAI has proposed limits based on the type of insurance, distribution channel, complexity of the product and the work required to sell and service it.
For individual linked and non-linked insurance products, commissions paid to intermediaries would range from 5 per cent to 20 per cent depending on the premium-payment term. Agents could receive between 6.25 per cent and 25 per cent.
Pure-term insurance would be treated differently. The proposed first-year commission is 25 per cent for intermediaries and 30 per cent for agents, followed by renewal commissions of 7.5 per cent and 10 per cent respectively.
Single-premium savings products would carry considerably lower commissions of around 1-2 per cent. For single-premium pure-term products, the proposed range is 7.5-10 per cent.
The regulator is proposing separate limits for general and health insurance.
For motor third-party insurance, intermediaries would receive no commission, while agents and associates could receive 2.5 per cent. On motor own-damage, personal accident and legal liability covers for new vehicles, commissions would be capped at 5 per cent for intermediaries and 10 per cent for agents and associates.
For first-time individual health insurance sales, the proposed commission is about 15 per cent for distribution entities and 20 per cent for agents. Renewal commissions would be limited to 5 per cent for distribution entities and 10 per cent for agents and associates.
IRDAI has left room for additional incentives where insurance products are sold in underserved areas, allowing rewards above the normal commission limits in such cases.
The proposed rules go beyond the amount insurers spend on distribution. They also address how insurance is sold, particularly through banks and non-banking financial companies.
IRDAI has proposed prohibiting the compulsory bundling of insurance with credit or loans. Certain combinations of insurance and lending products could still be permitted, but customers could not be forced to purchase an insurance policy simply because they were taking a loan.
The proposal addresses a longstanding area of concern in insurance distribution, where customers obtaining loans or other financial products may also be sold insurance through the same institution.
The regulator has also proposed banning volume-linked and reward-linked incentives for employees of banks and non-banking financial companies who sell insurance. It wants greater accountability where mis-selling occurs and has proposed using illustrations to help customers recognise such practices.
One of the more significant changes would make it easier to establish responsibility for an individual sale.
IRDAI has proposed linking the identity of the person who sold a policy directly to that policy. Information about incidents of mis-selling could also be placed in the public domain, while commissions could be clawed back where mis-selling is established.
The measures would be accompanied by greater disclosure requirements. Insurers and large distributors would have to publish their commission policies and remuneration structures in simple language, making it easier for policyholders to understand how sellers are compensated.
Cost audits would also become mandatory across insurers’ expenses, including payments to intermediaries and non-monetary incentives. Insurance distribution entities earning more than ₹100 crore in insurance-related revenue would face similar audit requirements.
The regulator has separately proposed reducing the regulatory fee paid by insurers from 0.05 per cent to 0.04 per cent of premium, subject to a maximum payment of ₹20 crore.
Another part of the consultation paper looks at the infrastructure through which insurance products are distributed. IRDAI has proposed Market Infrastructure Institutions for insurance as digital, pull-based alternatives to conventional distribution, identifying Bima Sugam as one such platform.
Taken together, the proposals would change both sides of the insurance business: how much insurers can spend to acquire and service business, and how distributors are paid for selling policies.
Lower commissions could reduce distribution costs, but they would also require insurers and intermediaries to reconsider existing sales models, particularly in products that depend heavily on agent or bank-led distribution. The phased expense reductions would similarly require insurers with higher cost structures to bring them down over several years.
For policyholders, the most direct implications would be lower costs if the savings are passed through, greater visibility into distributor remuneration and stronger safeguards against being pushed into insurance products they did not seek.
The measures remain proposals and are subject to consultation. Their eventual effect will depend on the final regulations IRDAI adopts and how insurers and distributors adjust their business models.
The direction of the proposed framework, however, is clear: IRDAI wants a larger share of the money paid by policyholders to support insurance coverage and benefits, while putting tighter limits on what can be absorbed by expenses, commissions and sales incentives.